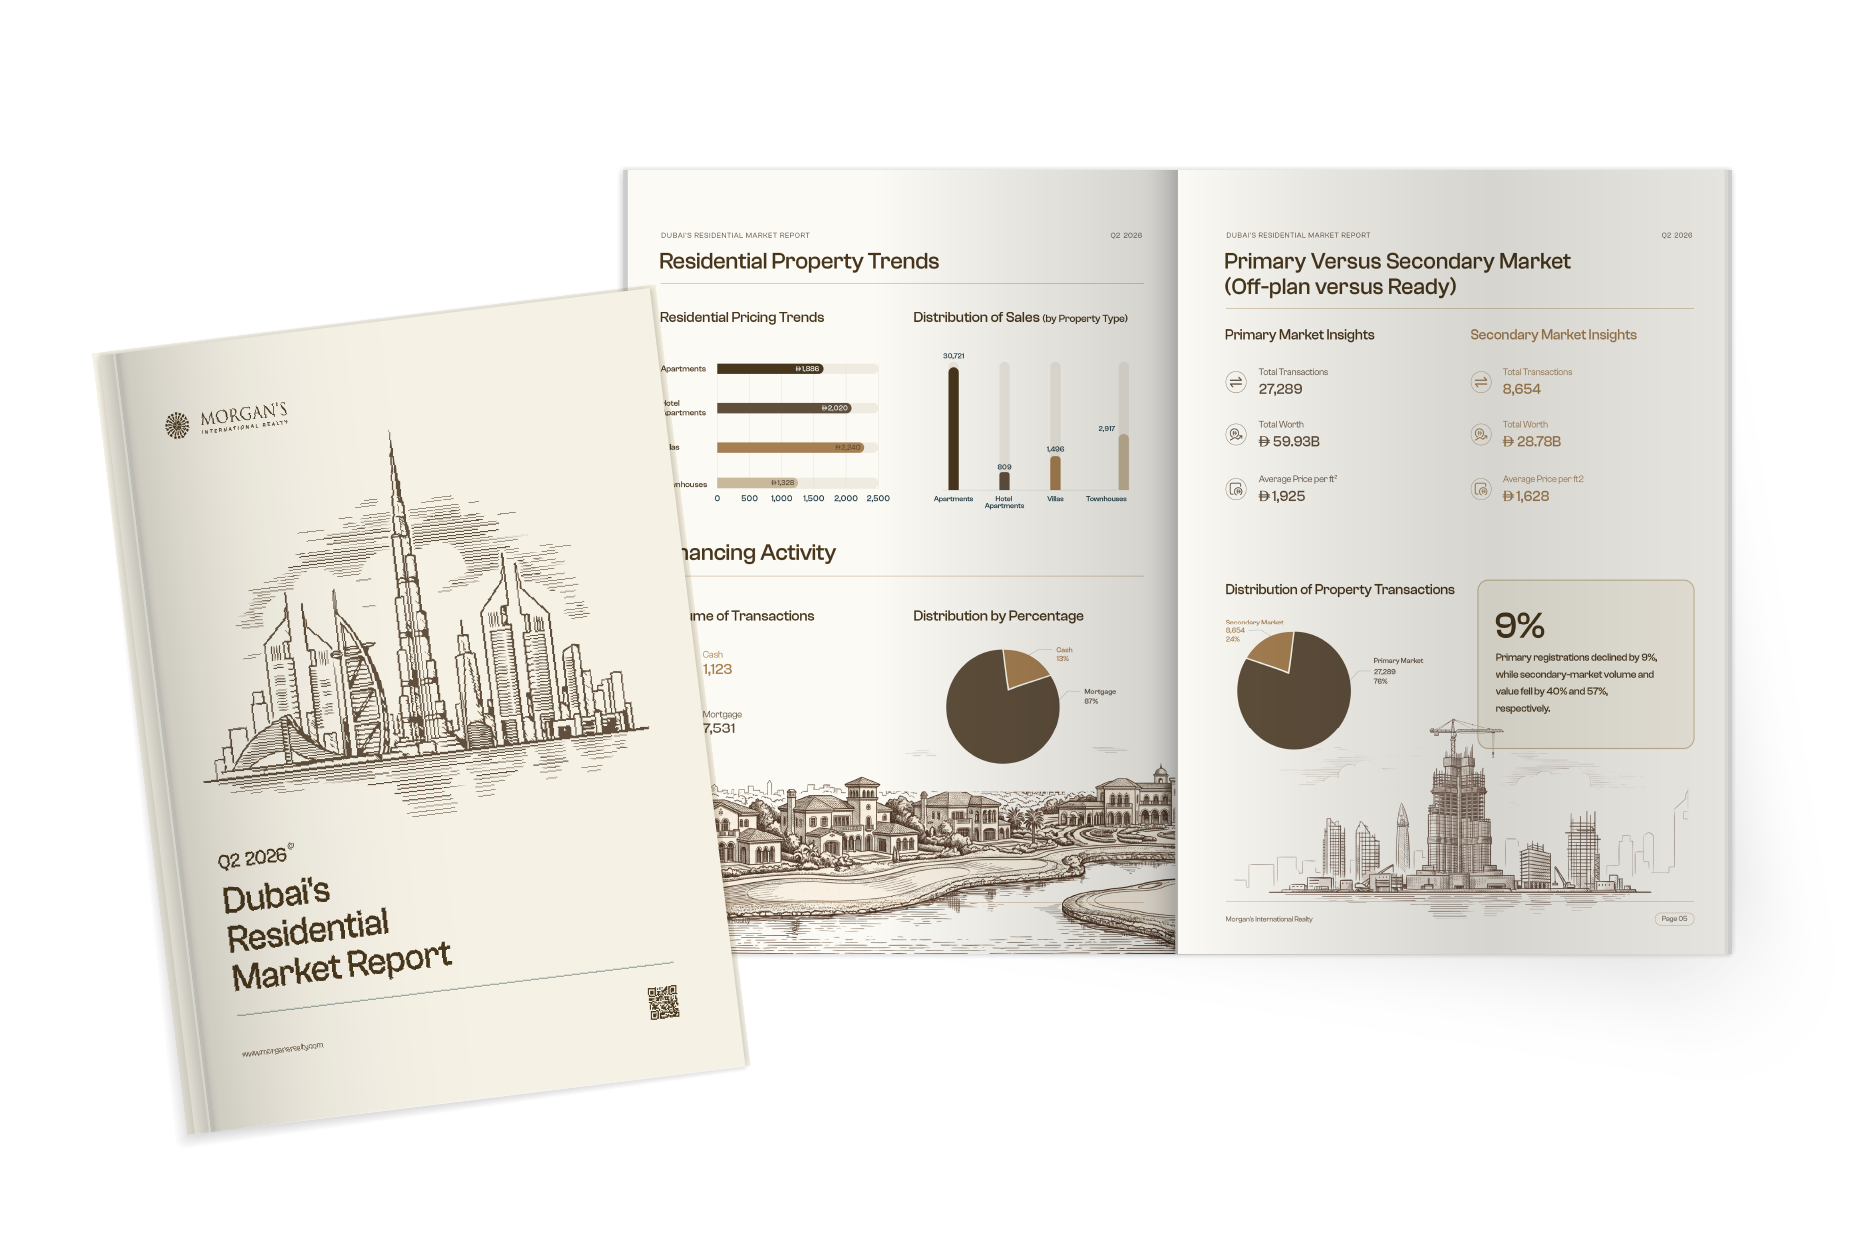
Q2 2026 marked a decisive break from the record pace that had defined Dubai's residential market. In the first full quarter to unfold against the regional conflict, transaction volume fell by 20% and value by 37% quarter-on-quarter. Yet average transacted pricing declined by only 3%, revealing a market in which liquidity contracted far faster than property values. Even after this adjustment, transaction activity remained above both five-year and ten-year quarterly averages.
Key Highlights

  • 35,943:Residential transactions recorded in Q2 2026 down 20% quarter-on-quarter, but still approximately 10% above the five-year quarterly average.
  • AED88.7B:Total transaction value, down 37% quarter-on-quarter as liquidity and high-value activity contracted more sharply than pricing.
  • AED 1,777 per sq. ft:Average transacted price, declining by only 3% and indicating limited market-wide repricing despite weaker activity.
  • 87%:Share of ready-market transactions financed by mortgages, as cash-funded purchases fell by 75% and end-users became the market’s main source of resilience.
  • 93%:Share of primary-market activity generated by initial developer sales, representing 25,434 transactions alongside 80 project launches.
  • 1,059:Transactions completed above AED 10 million, including 140 super-prime transactions and 18 trophy-property transactions.
  • 115,992:Rental transactions recorded during the quarter down 19%, while median rental pricing declined by 7% to AED 93 per sq. ft.
  • 472,616:Units remaining in Dubai’s development pipeline, with 62% scheduled for 2027 and 2028 making delivery timing the market’s next major structural test.

Fill out the form to download the full report