Share
Are Branded Residences in Dubai Worth the Premium? H1 2026 Insights
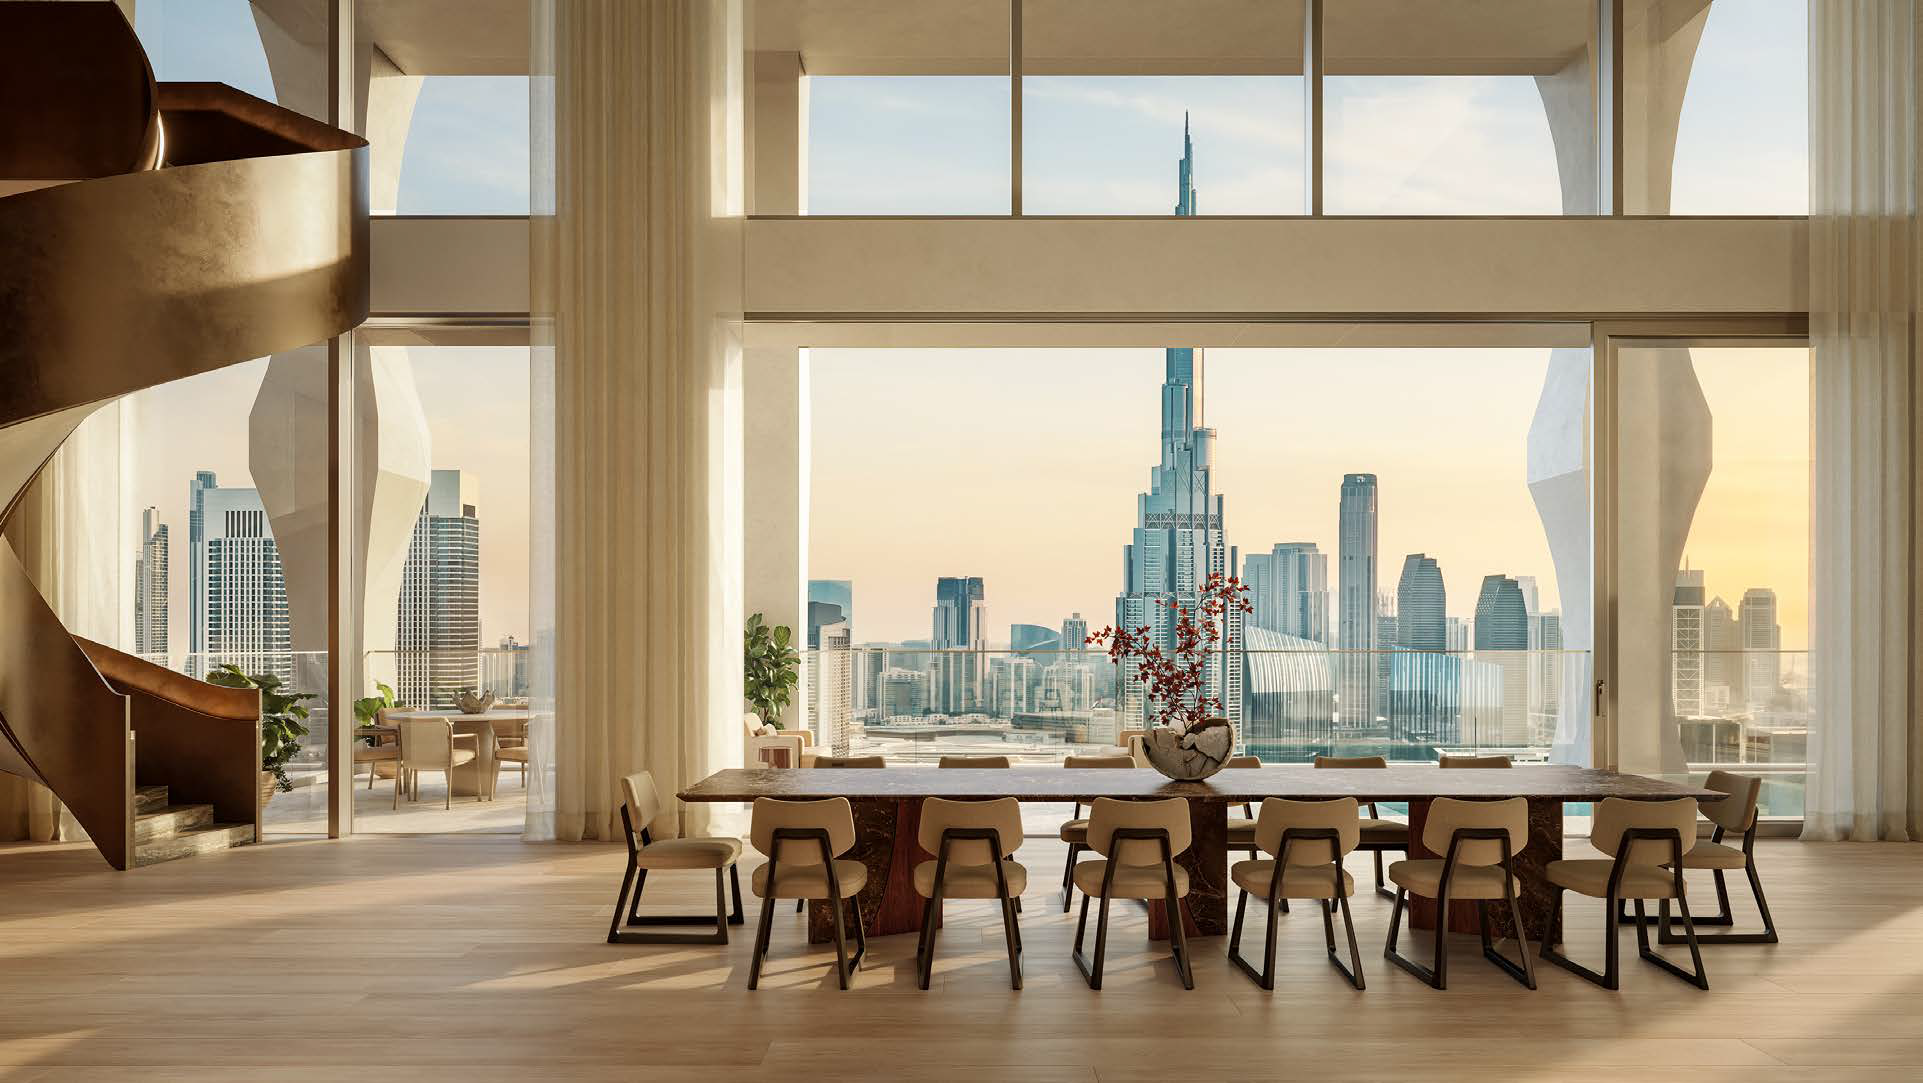
Branded residences in Dubai can justify a higher purchase price when their location, design, services and management provide lasting value. However, a recognised name alone does not establish investment quality. Dubai’s branded residences performance in H1 2026 highlights why buyers need to examine the property behind the brand.
According to Morgan’s International Realty’s H1 2026 analysis, branded residences achieved an average price premium of approximately 56% over the non-branded properties used in its comparison. The sector recorded 4,648 transactions worth AED 22.21 billion during the first six months of the year. Read Morgan’s H1 2026 market analysis.
For buyers considering branded residences in Dubai, the central question is straightforward: what does that additional purchase price actually buy?
What are branded residences?
Branded residences are homes associated with a recognised brand through an agreement covering elements such as design, identity, services or management. The brand’s involvement varies between developments.
That distinction matters when comparing properties. Buyers should establish whether the brand will operate the residences, provide defined services, oversee design standards or primarily license its name. Each arrangement creates a different ownership proposition.
A residence intended as a primary home should be assessed against the owner’s lifestyle requirements. A property purchased for rental income also needs to demonstrate that its income potential supports its acquisition and operating costs.
How did Dubai branded residences perform in H1 2026?
Morgan’s published H1 2026 findings show a market with substantial transaction activity and a sizeable pricing premium, alongside lower year-on-year sales.
| Performance measure | H1 2026 result |
|---|---|
| Branded residence transactions | 4,648 |
| Total transaction value | AED 22.21 billion |
| Transaction volume change versus H1 2025 | −21% |
| Transaction value change versus H1 2025 | −47% |
| Average achieved branded price | USD 997 per sq ft |
| Average non-branded comparison price | USD 641 per sq ft |
| Average branded residence price premium | Approximately 56% |
| Under-construction share of transaction volume | 82% |
Source: Morgan’s International Realty — Dubai’s Branded Residences Market in H1 2026. Figures cover January–June 2026; percentage changes are rounded.
These measures answer different questions. Transaction volume measures activity. Total sales value measures the money exchanged. Price per square foot helps compare pricing, although the mix of properties still matters. None independently establishes the return earned by an owner.
What does Dubai’s 56% branded residence premium mean?
The branded residence price premium describes the difference between average prices in the branded and non-branded groups being compared.
Using the published figures:
Price premium = (USD 997 ÷ USD 641 − 1) × 100 ≈ 56%.
This is a comparison between groups of properties during a reporting period. It does not mean that branded residences appreciated by 56%, generated a 56% investment return or will achieve the same premium on resale.
Nor does the comparison establish how much of the difference comes from branding alone. Location, waterfront access, building quality, unit size and transaction composition can influence the result.
For an individual purchase, a more useful comparison is between homes with similar locations, views, specifications and completion status. The buyer can then assess whether the remaining price difference is supported by meaningful benefits.
Does lower transaction value mean branded property prices fell?
A decline in aggregate sales value does not, by itself, demonstrate an equivalent decline in property prices.
For example, a market selling fewer large penthouses and more smaller apartments could record a substantial reduction in total transaction value without every property becoming cheaper.
Morgan’s H1 2026 analysis attributes the changed sales composition to a greater weighting towards smaller units, lower ticket sizes and non-prime inventory. It also reports broadly unchanged average achieved pricing and overall activity compared with H2 2025. View the performance breakdown.
Buyers should therefore examine recent transactions in the specific development they are considering. A citywide headline offers context; comparable sales provide more relevant evidence for an offer.
When is a branded residence worth paying more for?
A premium becomes easier to assess when it is connected to identifiable benefits.
| Factor | What a buyer should examine |
|---|---|
| Location | Comparable alternatives, access, surrounding development and the durability of the view |
| Design and specification | Layout efficiency, materials, privacy and construction quality |
| Brand involvement | The brand’s precise responsibilities and duration of involvement |
| Services | What is included, what costs extra and who delivers it |
| Operating costs | Service charges, management fees and maintenance obligations |
| Resale evidence | Completed transactions for comparable units and the depth of the buyer market |
For a homeowner, privacy, service and convenience may justify expenditure that does not produce a proportional rental return. That can be a reasonable lifestyle decision.
For an investor, the financial assessment needs to stand separately. A higher achievable rent must be considered alongside the higher purchase price and ongoing expenses.
Off-plan vs ready branded residences in Dubai
Buyers comparing off-plan branded residences with completed properties should distinguish between promised performance and observable performance.
An off-plan assessment depends on the developer’s delivery record, construction progress, contractual specifications, payment obligations and planned operating arrangements. A payment plan changes when capital is required; it does not establish whether the purchase price represents fair value.
A ready property allows a buyer to inspect the finished residence and investigate current building operations. Where available, actual leases, service charge statements and completed resales provide evidence that forecasts cannot.
| Buyer question | Off-plan residence | Ready residence |
|---|---|---|
| What quality can I assess? | Specifications, plans and relevant completed projects | The completed unit and common areas |
| How can I evaluate services? | Proposed arrangements and contractual commitments | Existing service delivery and management |
| What supports rental assumptions? | Comparable properties and clearly labelled forecasts | Actual leases where available |
| What costs should I review? | Payment schedule and estimated operating costs | Acquisition costs and current operating expenses |
The appropriate choice depends on the buyer’s intended use, funding position and willingness to accept delivery uncertainty.
How to assess a branded residences investment in Dubai
Start with the unit’s economics before relying on the development’s reputation.
- Compare achieved sales prices. Use similar units and distinguish registered transactions from asking prices.
- Calculate income after expenses. Account for service charges, management, maintenance and vacancy assumptions.
- Check the brand agreement. Establish which benefits are contractually supported and how ongoing services are funded.
- Review competing supply. Consider comparable homes that may become available around the intended leasing or resale date.
- Test the exit assumptions. Assess who the next buyer would be and what evidence supports the anticipated resale price.
For rental analysis, a useful starting calculation is:
Net rental yield before financing = annual rental income after operating expenses ÷ total acquisition cost × 100.
Use consistent assumptions when comparing branded and non-branded properties. Projected rent for one development should not be presented as equivalent to achieved rent in another.
Explore Morgan’s branded residences research
A considered purchase begins with understanding the relationship between price, product and ownership costs. Morgan’s H1 2026 research provides the market context for that discussion.
Explore the Dubai Branded Residences H1 2026 analysis and full report, or speak with a Morgan’s advisor to discuss how a specific residence fits your objectives.
Frequently Asked Questions
Use the report to understand market activity and pricing benchmarks, then investigate the particular development and unit. Market averages provide a starting point for due diligence rather than a valuation for an individual home.
No. A higher rental income does not necessarily produce a higher yield when the acquisition price and operating costs are also greater. Buyers should compare net income relative to the total cost of ownership.
They can be, but the assessment depends on the purchase price, location, operating costs, rental evidence and resale prospects. Brand recognition should form part of the evaluation alongside the developer, completed product and management arrangements.
Related Posts
Dubai Property Investors Are Cautious for 12 Months, Confident for 3 Years: New Survey Data
Dubai Residential Market Recalibrates in Q2 2026